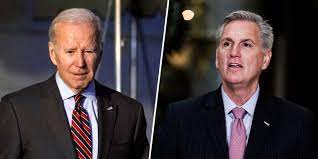
President Biden and Speaker McCarthy are running out of time. That’s what the numbers are telling us in the months since January, when the Treasury said it could employ “extraordinary measures” to remain under the ceiling for five months.
The most important “measure” is income tax collections. They look likely to fall significantly short of Washington’s expectations this filing season, dragged down by plunging receipts from capital gains taxes.
Capital gains taxes are likely to come in below the Congressional Budget Office projection of $315 billion for the full fiscal year of 2023. CBO’s forecast is down only $63 billion, or 17%, from last fiscal year’s record high of $378 billion that was produced by the eye-popping rise in stocks of 27 percent in 2021, as measured by the S&P Index .
Such a modest decline seems unlikely given that the stock market in 2022 had a dramatic reversal of fortune and plunged almost 20%. That’s a greater annual decline than in any year since 2008, when the S&P plunged 38% and capital gains taxes fell about 50% the next fiscal year, according to CBO.